I Spent 43 Years Watching Good People Pay Bills They Never Owed.
Bank Policy Said I Couldn't Tell Them. Retirement Says I Can.
There is money with your name on it sitting in a filing cabinet right now — an exemption, a program, a credit. Nobody is required to tell you it's there. This book is 52 of them, one phone call a week, with the exact words to say.
YES — SHOW ME THE 52 Instant download · Large, clear type · Reads on any device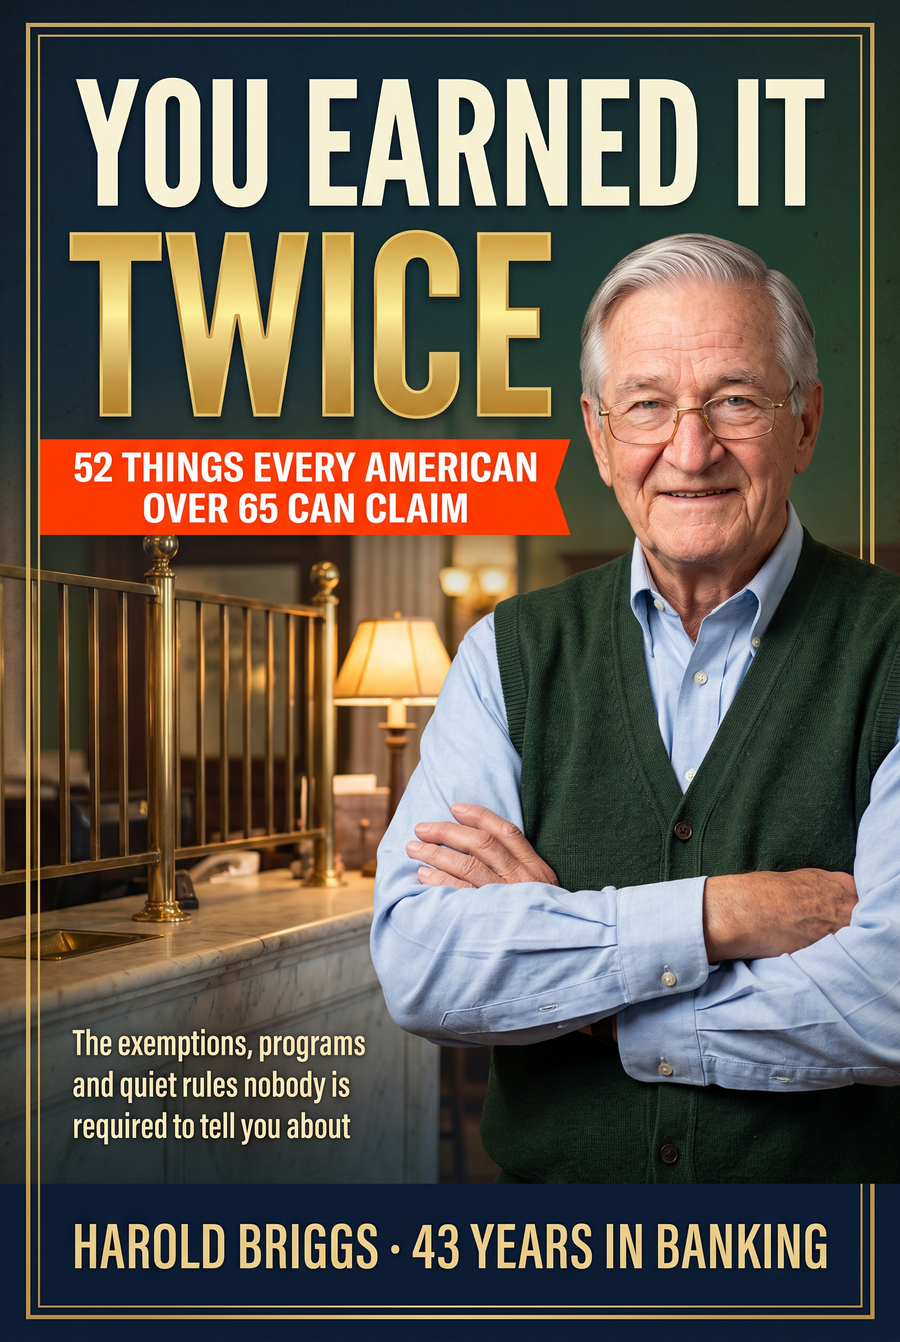
You've Paid Every Bill On Time For Fifty Years. That's Exactly The Problem.
- You've never missed a payment in your life — and you're proud of that, as you should be.
- Nobody has ever sat you down and explained what you stopped having to pay for when you turned 65.
- You've heard there are programs, but you assume they're for people worse off than you.
- Or you assume you'd get a letter if you qualified for something. You won't. Paper doesn't knock on doors.
- And somewhere underneath it all: you'd feel a little ashamed to ask, as though you were taking something.
Here is the sentence that cost my customers the most money over 43 years: never missing a payment is not the same as never overpaying.
Nobody lied to you. Nobody told you either. That's the whole game. The county doesn't have to mention the exemption. Social Security doesn't have to mention the option. Your utility company is under no obligation to advertise the senior rate — and believe me, they don't. Being eligible and being enrolled are two completely different things, and the law only works when you invoke it.
What Being The Last To Know Actually Costs
These are ordinary, common programs. Not loopholes, not tricks — rules written for people your age that simply require somebody to fill in a form. Here is roughly what an average household leaves on the table in a single year:
| What goes unclaimed | Per year |
|---|---|
| Property tax exemptions never applied for | $400 – $1,200 |
| Medicare premium help for those who qualify | up to $2,400 |
| Prescription cost help (Extra Help) | hundreds |
| Heating and utility programs | $200 – $600 |
| Tax deductions for people over 65 not taken | varies |
| The cost of nobody telling you | often $1,000+ |
Illustrative ranges only — your figures depend on your state, your county and your income. Every program in this book has its own rules and its own limits, and the book tells you where to check yours.
The book costs $29. One successful phone call usually returns that many times over — and then keeps returning it every year for the rest of your life.
52 Calls. One A Week. A Year From Now You'll Have Made Them All.
Every entry gives you the same five things: what it is in plain English, who it's for, what it can be worth, the exact sentence to say on the phone, and where people get caught. No jargon. Large, clear type.
The House
The homestead exemption, the extra senior exemption that sits on top of it, the assessment freeze, the circuit breaker credit (and the renter's version of it), veteran and disability exemptions, tax deferral, how to appeal, how to ask about past years — and the re-filing a surviving spouse must do that nobody mentions.
The Check You Already Get
Your three numbers. What claiming early actually costs. The survivor rule — the one that decides what your spouse lives on for the rest of their life. The earnings test and the part nobody explains. The twelve-month reset button. Spousal and divorced-spouse benefits.
The Return
The senior deduction and the four tax years it exists for. The three-layer stack and what it shields. Why you must still file even when you don't have to. The over-withholding trap. How to amend a past return — and the free help that is genuinely free.
The Doctor Bills
The premium quietly leaving your check every month. QMB, SLMB and QI. Why you should apply even when you think you earn too much. Extra Help for prescriptions. SHIP. IRMAA and the appeal almost nobody files. The two penalties that never go away.
The Household Bills
Heating assistance and crisis help. Weatherization. The phone and internet discount. Your utility company's own senior programs. SNAP after sixty — and yes, sixty, not sixty-five. Insurance discounts. The subscription audit. The free screening tool that checks dozens of programs at once.
When Life Changes, And Keeping It
Veterans' Aid and Attendance. The surviving spouse's first ninety days, in order, calmly. The caregiver's file. When one spouse enters care. The scam chapter. The January afternoon that keeps it all current. And the kitchen table conversation with the person who will outlive you.
Plus: the Sentence Cards — every phone script on tear-out pages in large type · the 52-week call log · and the ledger page for writing down what you get back.
What Happens After The First Phone Call
"I have owned this house since 1981 and I have never once been told about the senior exemption. I called the assessor on a Tuesday morning with Harold's sentence written on a pad in front of me. Took eleven minutes. My bill next year is lower and they are looking at last year too."
"I bought it for my mother, who is 81 and would never in her life ask anyone for anything. The chapter about not feeling ashamed is the one that got through to her. She has made four of the calls herself now."
"My husband claimed at 62 without telling me and he passed four years ago. I did not know until I read the survivor chapter why my check is what it is. I wish we had both read this in 2009. I have made my daughter read it."
"I am a retired electrician and I do not spend money on books. I qualified for the prescription help. That was the whole book paid for in one afternoon and then some, every month from here on."

Forty-three years on the other side of the counter.
I started as a teller in 1969, counting other people's money through a window, and I retired as the branch manager of the same small-town Ohio bank. I watched a whole town's money go by, twice a month, for four decades.
And every January and every July, the retired people of my town came in to pay their property tax. A man would tell me proudly he had never missed a payment in his life, and I would be looking at a bill hundreds of dollars higher than it needed to be. Bank policy said it wasn't my place to say anything.
Well. I'm retired now. It is absolutely my place.
This book is not written like a textbook. It is written the way I would have explained it to you across that counter, if I had been allowed to — one thing at a time, in plain words, with the exact sentence to say written out so you don't have to think of it yourself.
— Harold Briggs
💳 The Banker's Guarantee — 7 Days
Read the first part. Make one call. If this book doesn't show you at least one thing worth picking up the phone for, reply to your download email within 7 days and I'll refund every cent. You keep the book. That's not me being generous — that's just sound banking.
Everything You Might Be Wondering
What exactly do I get?
A 354-page PDF book, sent to your email the moment you order. Large, clear type. It works on a phone, a tablet, a computer, or you can print the pages you need. You also get the Sentence Cards, the 52-week call log and the ledger page.
Is this financial advice?
No, and I'm careful about that. This is general educational information about programs that exist. Every one of them has rules that vary by state, by county and by income, and they change every year. The book tells you exactly who to call to confirm your own situation. Nothing here replaces your accountant, your attorney or the agency itself.
I don't own my home. Is this still for me?
Yes. Several of the property chapters have a renter's version, and the Social Security, tax, Medicare and household-bill parts — which is most of the book — have nothing to do with owning a house.
We're comfortable. Aren't these programs for poor folks?
Some are income-limited and some aren't. Property tax exemptions, Social Security claiming, the senior deduction and the Medicare appeal have nothing to do with being short of money. And the income limits are often higher than people assume — a good many households rule themselves out on a guess.
Am I too old for this to be worth it?
Some of these are worth more the older you are, not less. And several can be asked about for past years. The book tells you which ones and how to ask.
I'm buying this for my mother or father. Will they manage it?
That's who a good deal of it is written for. Large type, one call at a time, and the exact words to say. There's a chapter written specifically for the adult son or daughter, and a caregiver's file to fill in together.
What if it isn't for me?
Reply to your download email within 7 days and you get every cent back, no questions, and you keep the book.
A Year From Now You'll Either Have Made These Calls — Or You'll Be Another Year Into Not Knowing.
Dorothy paid a bill she didn't owe for nine years. The county did nothing wrong. They simply never mentioned it. The only question that matters is how many years you are into your own version of that.
until the launch price ends
Less than one month of what you may be overpaying.
By clicking, you agree to our Terms and Privacy Policy.
You Earned It Twice · by Harold Briggs
What's Inside · Privacy Policy · Terms of Service · Refund Policy
© 2026 Harold Briggs. General educational information only — not personal legal, tax or financial advice. Program rules vary by state, county and income and change every year. Always confirm with the agency involved or a licensed professional before you act. Results vary from person to person.
ONE LAST THING FROM HAROLD
One call usually pays for this book many times over.
Most readers find something in the first part — and a good many find it was there last year too. It costs ten seconds of courage and a phone call you can make in your slippers.
7-day refund if it isn't what you needed.
CLICK HERE FOR INSTANT ACCESS